

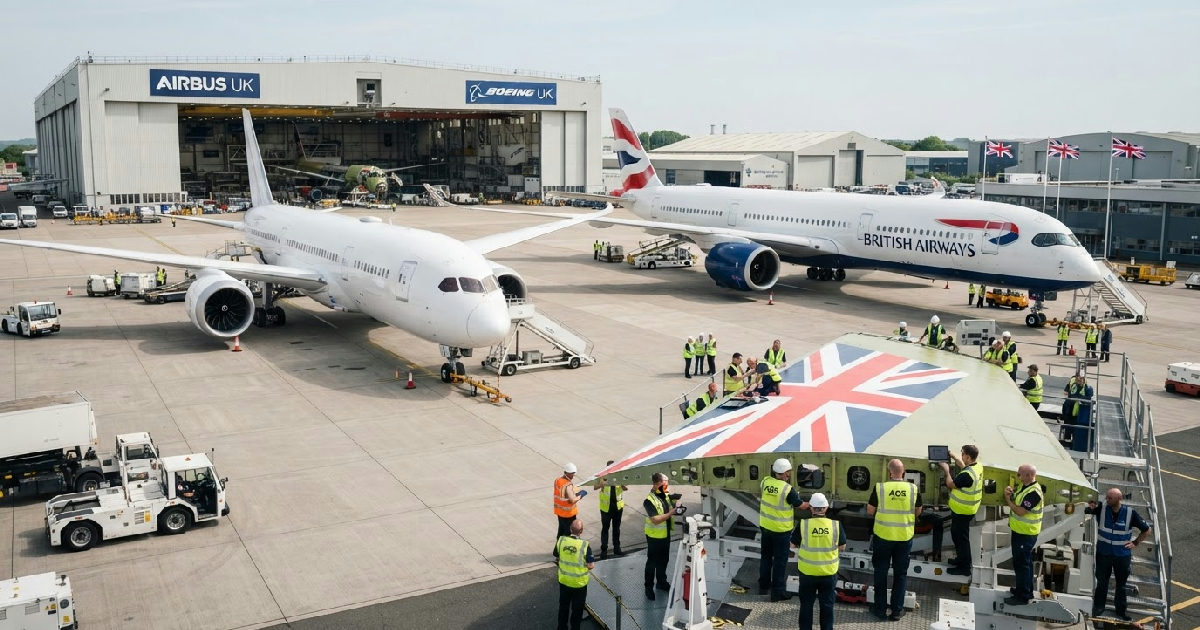
The global commercial aviation market is experiencing a recovery in aircraft deliveries, reaching its highest levels since 2018 and supporting demand across the UK aerospace supply chain. The increase follows the pandemic-era downturn and comes amid a substantial global aircraft order backlog, providing longer-term demand visibility for manufacturers and suppliers, including those in the UK.
Data published by aerospace trade association ADS Group points to a recovery in aircraft deliveries and continued demand for new aircraft. Global commercial aircraft manufacturers delivered 132 aircraft in October 2025, a 67% increase compared with October 2024. The strong performance has continued, solidifying the industry’s return to pre-pandemic production rates and securing its economic contribution.
A sustained recovery in UK aerospace sector aircraft deliveries
The positive trend in 2025 laid the groundwork for even stronger results in 2026. For the full year 2025, a total of 1,411 aircraft were delivered, a 25% increase over 2024. The 2025 total of 1,411 deliveries was the highest since 2018 and exceeded ADS’s high-growth forecast of 1,340 aircraft by 71.
This momentum has carried through into 2026. Manufacturers delivered 903 commercial aircraft globally between January and August 2026, a 9% increase compared with the same period in 2025. In May 2026, manufacturers delivered 142 aircraft, a record for the month and a 45% increase year-on-year. This indicates that production lines are adapting to meet the intense global demand for new, more fuel-efficient aircraft.
While delivery rates are climbing, new orders show a more complex picture. Manufacturers recorded 127 aircraft orders in October 2025, a 12% decline year-on-year. However, order activity strengthened in the following months. A total of 1,331 aircraft orders were recorded in the first half of 2026, a 15% increase compared with the same period in 2025.
Sustaining this growth demands ongoing investment in manufacturing capability. Projects focused on developing industrial facilities are crucial for long-term competitiveness.
The record-breaking backlog securing UK jobs
The foundation of the sector’s long-term health is its staggering order backlog. By August 2026, the global commercial aircraft backlog had reached 17,010 aircraft. ADS estimated that the backlog could represent up to £391 billion in value to the UK economy at current production rates.
At current production rates, the backlog represents more than 12 years of work for the UK’s aerospace supply chain. The backlog supports long-term demand across the UK aerospace supply chain. Around 88% of UK aerospace jobs are located outside London and the South East.
ADS data put UK aerospace output at approximately £105,000 per worker in 2023. The article should cite the underlying report for the comparison with the UK average.
Aimie Stone, Chief Economist at ADS, highlighted the importance of a steady production tempo. “October’s delivery figures signal that the industry is moving towards a more stable and sustained delivery drumbeat,” she said in late 2025. “The priority now is to maintain this momentum.” Her comments reflect the industry’s focus on translating a full order book into consistent factory output.
Single-aisle jets dominate demand
Single-aisle aircraft accounted for the largest share of new orders in the first half of 2026. In the first six months of 2026, a record 1,074 single-aisle jets were ordered, a 59% jump compared to the same period in 2025.
Single-aisle aircraft accounted for approximately 81% of orders in the first half of 2026. The Airbus A320 family is one example of a programme involving UK aerospace manufacturing, including wing production.
Demand has been supported by airlines’ interest in fuel-efficient aircraft for short- and medium-haul routes, alongside continued fleet renewal. In contrast, orders for widebody aircraft, used for long-haul flights, stood at 257 in the first half of 2026. Widebody aircraft accounted for the remaining 257 orders, indicating a smaller share of demand during the period.
This focus on single-aisle aircraft influences manufacturing strategies across the globe. Industrial players are responding with new production capabilities to meet evolving market needs.
From pandemic crisis to production rebound
The current strength of the UK aerospace sector is even more remarkable when set against the severe disruption of the COVID-19 pandemic. The COVID-19 pandemic severely disrupted global aviation in 2020, reducing demand for new aircraft and prompting manufacturers to cut production. The downturn prompted restructuring across the sector, with UK aerospace manufacturing employment falling by approximately 14,000 between 2020 and 2021.
Major employers, including Rolls-Royce and Airbus, also announced workforce reductions during the downturn. Rolls-Royce undertook its largest-ever restructuring, while Airbus reduced its UK workforce by 1,700 roles. The recovery was uneven, with aircraft deliveries declining in 2024 before rebounding in 2025. The increase in global deliveries during 2025 and the first eight months of 2026 suggests that the market has continued to recover, although manufacturers still face production constraints.
Navigating future challenges and opportunities
Despite the positive outlook, the industry is not without its challenges. Persistent supply chain issues and a volatile geopolitical climate continue to test manufacturers. In December 2025, ADS Chief Economist Aimie Stone called for a stable policy environment, saying that government policy should support the industry’s progress rather than place additional burdens on manufacturers.
This call to action has been met with some support. At the Farnborough International Airshow in July 2026, the UK government announced £600 million in support for the aerospace industry. The package included more than £500 million for aerospace research and technology projects, alongside a separate £100 million fund to help suppliers expand their capabilities. The Aerospace Technology Institute programme co-funds civil aerospace research and technology development, including work aligned with the UK’s aerospace technology strategy and sustainability objectives.
The sector’s long-term prospects also depend on its ability to develop and retain skilled engineers. Addressing workforce shortages alongside supply-chain constraints will be important as manufacturers seek to increase production.
